
ALIGNING FAMILY AND CAPITAL WITH A 100-YEAR VISION
The Charitable Remainder Trust
Preparing the Money for the Family Through Tax-Efficient Giving
How a highly appreciated asset may be used to create lifetime income, potential tax benefits, and lasting charitable impact…all within one planning structure.
Paradiem LLC is a registered investment advisor. This presentation is provided for educational and informational purposes only, and should not be construed as individualized investment, tax, legal, or estate-planning advice. The concepts discussed are intended to encourage thoughtful conversations around family legacy and generosity and may not be appropriate for every individual or family. Any discussion of tax or estate-planning concepts is general in nature, so please consult your own financial, tax, legal, or other professional advisors regarding your specific circumstances. 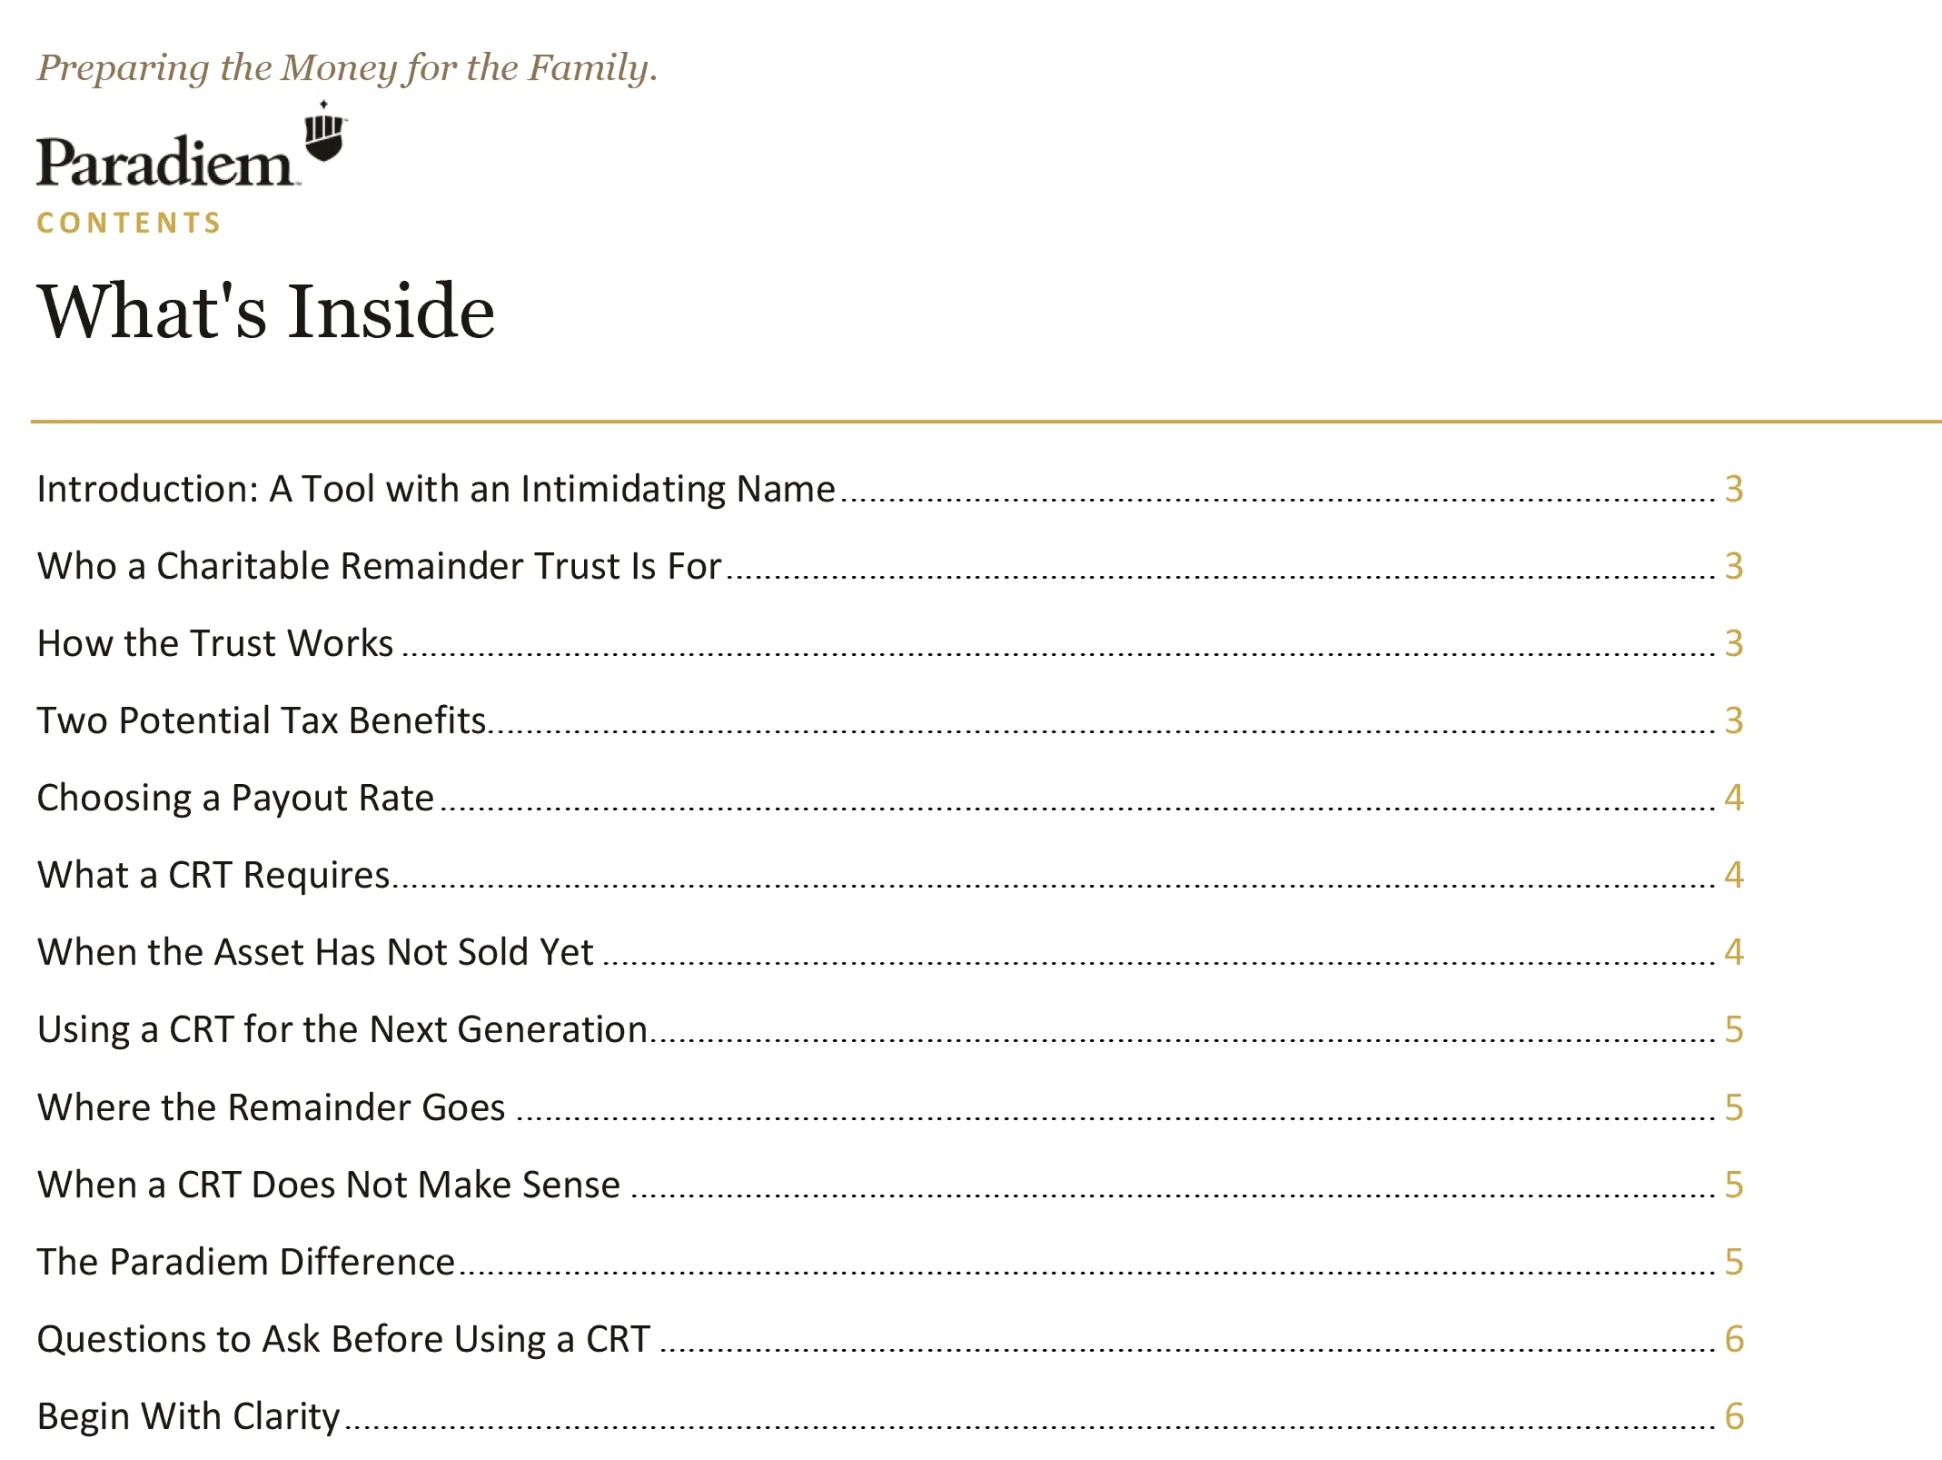
Introduction: A Tool with an Intimidating Name
Many successful families reach a point where they would like to give a meaningful gift to a cause or community they care about, without giving up the income they still need to live on. It has an intimidating name — the charitable remainder trust, or CRT — but the concept behind it is more approachable than the name suggests and is one planning tool designed to address both objectives.
A CRT allows a family to contribute a highly appreciated asset, such as a business or a piece of real estate, into an irrevocable trust. The trust may then sell the contributed asset without immediately recognizing capital-gains tax at the trust level, invest the proceeds, and make distributions to the designated beneficiaries. Those distributions may be taxable depending on the trust’s income and applicable tax rules. Whatever remains when that income stream ends passes to charity.
This tool is about getting the money ready for the family.
Who a Charitable Remainder Trust Is For
A CRT is generally most appropriate for families who already have a genuine charitable intent — who want to make a real difference beyond simply providing for themselves or their children. From there, the circumstances that typically make a CRT worth considering include owning a business, real estate, or a concentrated stock position with significant built-in appreciation, especially when the family is preparing to sell or diversify.
In one sentence: a CRT is a tool that, when appropriately structured, may provide tax benefits and an income stream to designated beneficiaries, with the remaining assets ultimately passing to charity.
How the Trust Works
A CRT is typically used for a portion of a larger transaction, not the entire sale. The goal is for the trust to fit within the family’s full plan — one that takes care of the family, provides for their children, and accomplishes what they want to do charitably — rather than standing on its own.
The decision is irrevocable. Once an asset is placed in the trust, that decision generally cannot be undone. For business owners, who are often selling something that represents a lifetime of work, that irreversibility understandably raises questions. Families who begin the conversation years before a sale, rather than in the weeks leading up to it, tend to arrive at the decision with far more confidence and far less anxiety about getting it wrong.
Timing is also critical. Once a sale has progressed sufficiently, contributing the asset to a CRT may no longer produce the intended tax treatment. A letter of intent or signed agreement can affect the analysis, so qualified tax and legal counsel should evaluate the transaction before the asset is transferred.
Two Potential Tax Benefits
A CRT offers what is often described as a double tax benefit. First, a contribution to a qualifying CRT may generate a partial charitable income-tax deduction based on the present value of the charitable remainder interest, subject to applicable tax rules and limitations. Second, a qualifying CRT generally does not recognize immediate capital-gains tax when it sells contributed appreciated assets. However, subsequent distributions to non-charitable beneficiaries may carry taxable income or capital gains under applicable tax rules.
In practice, families do not always place an entire asset into the trust. A portion may be sold outside the trust to fund other goals — a new house, a new venture — and that portion is taxed normally, though the charitable deduction can help offset some of that gain. The remaining income-producing assets inside the trust then provide income for the family for the rest of their lives.
Tax deferral may allow more of the contributed asset to remain invested within the trust to support its income and charitable objectives.
Choosing a Payout Rate
Families choose a payout rate when the trust is established, generally somewhere between 5% and 7% of the trust’s value, recalculated each year. For illustration only, if a $10 million trust were subject to a 7% annual unitrust payout, the calculated distribution for that year would be $700,000. Actual distributions will depend on the trust’s structure, value, and applicable terms.
Because distributions may depend on the trust’s value, market declines can reduce both trust assets and future distributions. Investment performance and subsequent recovery are not guaranteed.
What a CRT Requires
A CRT can be a powerful tool in the right situation, and a poor fit in others. It tends to work well only when the following are true.
WHAT A CHARITABLE REMAINDER TRUST REQUIRES
A CRT can be a powerful tool, but it tends to work well only when three conditions are actually true.
1. Genuine Charitable Intent. A CRT is not simply a tax-avoidance vehicle. It works best for families who want to make a real charitable impact and see the tax efficiency as a meaningful byproduct, not the entire point.
2. Timing Before the Sale. A trust generally must be funded before a signed agreement to sell the underlying asset. A letter of intent may still leave room, but once a sale is signed, the option is gone.
3. Integration With the Full Plan. A CRT works best as one piece of a coordinated plan — alongside what a family wants for their own income, their children, and their giving — rather than a stand-alone strategy chosen in isolation.
When the Asset Has Not Sold Yet
An asset contributed to a CRT may remain unsold for an extended period. In these situations, the trust can be designed as a net income trust, which pays out only if the trust itself generates income, with a triggering event, generally the eventual sale, that converts it to a standard payout structure. Designing this possibility from the outset is one more reason a CRT should be built around a family’s full circumstances rather than a generic template.
Using a CRT for the Next Generation
A qualifying CRT must generally satisfy a requirement that the actuarial value of the charitable remainder interest equals at least 10% of the initial net fair market value of the property contributed to the trust. Because the calculation incorporates factors such as beneficiary age, payout rate, and applicable IRS assumptions, satisfying the remainder requirement can be more difficult for younger beneficiaries.
Some families use a CRT not for themselves, but to provide a lifetime income stream for adult children, particularly when passing down a highly appreciated asset directly would raise concerns about how that inheritance might be used. A trust structured this way can provide reliable income for a child’s lifetime while still directing the eventual remainder to charity — though the same age-based calculations apply, and the structure works only when it fits the child’s age and the family’s broader intentions.
Where the Remainder Goes
When both lifetimes covered by the trust have ended, the remaining assets pass to charity. Many families choose to direct that remainder to a donor-advised fund rather than naming a specific charity outright. Using a donor-advised fund may provide flexibility for future charitable recommendations without requiring the CRT itself to be amended, subject to the sponsoring organization’s policies and applicable rules — a meaningful advantage given how much a family’s charitable priorities, and the charities themselves, can change over decades.
This approach also creates a natural opening to involve the next generation. Parents often direct a portion of the eventual gift toward causes they already care about, while leaving the rest for children, and sometimes grandchildren, to steward and direct as they grow into that responsibility. Families who involve children in giving decisions well before that transition tend to be more comfortable leaving a larger share undesignated.
When a CRT Does Not Make Sense
A CRT is generally not the right tool for someone without a genuine charitable intent. The tax benefits are real, but a family pursuing this structure purely to minimize taxes, without any interest in the charitable outcome, is usually better served by a different strategy.
Unrealistic expectations are also a common reason a CRT falls apart before it starts. Some proposed CRT structures may contemplate payout rates or timelines that cannot satisfy the required charitable remainder. A CRT is not a way to extract a lump sum quickly; it is a long-term income and giving structure, and it works only within the limits the tax code sets for it.
The Paradiem Difference
Paradiem’s approach starts with understanding a family’s broader goals—for themselves, their children, and their giving—before evaluating whether a CRT or another planning strategy may be appropriate.
That sequencing matters. Preparing the family for the money and preparing the money for the family are both necessary, but they work best in the right order and as part of one integrated plan — not as a series of disconnected strategies assembled one at a time.
Questions to Ask Before Using a CRT
If a charitable remainder trust seems worth considering, the following questions can help clarify whether it fits your situation before any decision is made.
1. Do we have a genuine charitable intent, or are we primarily looking for tax efficiency?
A CRT tends to work best when the charitable outcome is a real goal, not an afterthought.
2. Where are we in the sale process for the underlying asset?
A signed agreement to sell generally closes the door; a letter of intent may not.
3. How does this fit within our overall plan?
A CRT should support what you are already trying to accomplish for your family and your giving, not stand apart from it.
4. What payout rate fits our income needs and time horizon?
The appropriate payout rate depends on the trust’s structure, applicable tax requirements, income needs, and time horizon.
5. Are we funding this with the full asset, or a portion of a larger transaction?
A CRT may be funded with only a portion of an asset or larger transaction, depending on the family’s objectives and circumstances.
6. If this is for our children, are they old enough, and are we preparing them for what it means?
Age-based calculations apply, and the family conversation matters as much as the math.
7. Should the remainder go directly to a charity, or to a donor-advised fund?
A donor-advised fund may provide flexibility for future charitable recommendations without requiring amendments to the CRT, subject to the sponsoring organization’s policies.
8. How much lead time do we have before the transaction?
Beginning the planning process well in advance of a potential transaction provides more time to evaluate the structure, coordinate with tax and legal professionals, and become comfortable with an irrevocable decision.
Begin With Clarity
A charitable remainder trust is one tool among many, and it earns a place in a family’s plan only when it genuinely fits their full picture — their income needs, their children, and their charitable intentions together.
That is a conversation worth having alongside the rest of your estate, tax, and succession strategy, not apart from it.
Every conversation at Paradiem starts with a complimentary Family Capital Assessment, an introductory conversation designed to help us understand where your family and capital stand today, the goals you’re working toward, and areas that may warrant deeper exploration.
Recent Comments